Commercial Insurance Questions: A Complete Guide for Business Owners
Most commercial insurance questions boil down to one thing: will this policy actually be there when something goes wrong? That’s the commercial insurance questions that matters, and it’s the one this guide answers first. Whether you’re buying your first policy or reviewing one that’s grown stale, the goal is the same coverage that matches your real risk, not just a stack of paperwork.
I’ve sat across the table from enough business owners to know the fear isn’t abstract. It’s the client who slips on a wet floor, the laptop stolen from a parked car, the flood that shuts the shop for six weeks. A good policy doesn’t prevent those days. It decides whether you survive them.
What Is Commercial Insurance and Why Do Businesses Need It?
commercial insurance questions is coverage that protects a business against financial losses from accidents, lawsuits, natural disasters, employee injuries, and property damage. It exists because a single bad day a fire, a lawsuit, a data breach can otherwise wipe out years of work in an afternoon.
Without it, that bad day becomes a personal one. Owners without proper coverage often pay claims out of pocket, out of savings, or out of the business itself, which is why insurance is treated less as an expense and more as operating infrastructure like rent or payroll.
What Types of Business Insurance Should Small Businesses Consider?
Most small businesses build coverage from a handful of core policies: general liability (third-party injury and property damage claims), professional liability/E&O (mistakes in advice or services), workers’ compensation (employee injuries), commercial property (your building and contents), and commercial auto (business-use vehicles). A Business Owner’s Policy (BOP) bundles general liability and commercial property together, usually at a lower combined cost than buying each separately.
Which of these you actually need depends on your operations, not a generic checklist. A consultant giving advice needs E&O far more than commercial property coverage; a retail store with a storefront needs the opposite emphasis. Layer in commercial umbrella insurance once your standard limits start feeling tight relative to your contracts or client size.
What Are the Most Common Business Insurance Claims?
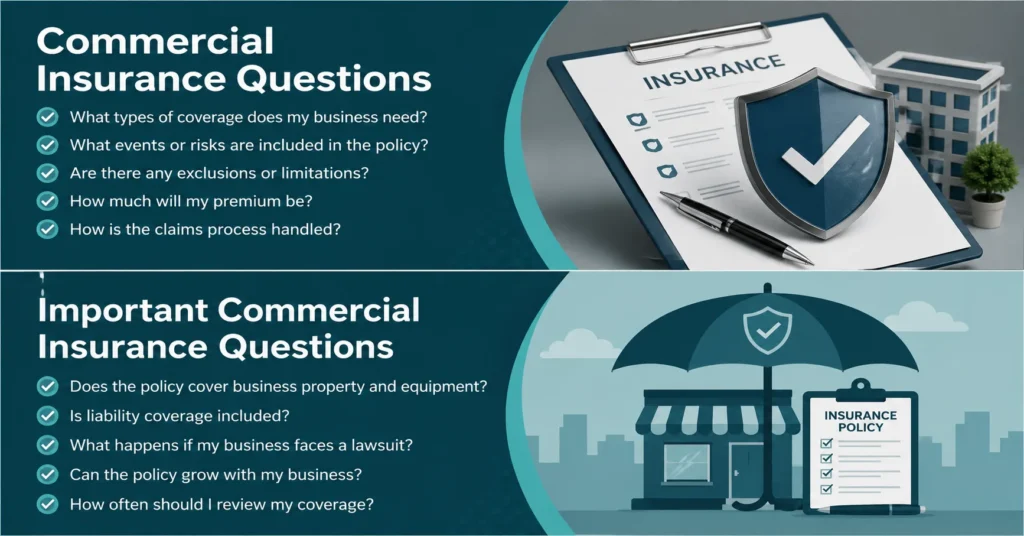
The most frequent commercial insurance questions claims are property damage, customer injuries on-site, and employee workplace injuries with cyberattacks and product liability claims rising fast in recent years. These aren’t rare, catastrophic events; they’re the ordinary cost of doing business with people, property, and the public.
That’s exactly why liability coverage isn’t optional in practice, even in states where it isn’t legally mandated. A single slip-and-fall lawsuit or a stolen laptop full of client data can cost more than years of premiums combined the math almost always favors carrying the coverage.
What Risks and Claims Would My Insurance Policies Actually Cover?
Before signing anything, get specific answers from your agent: what events trigger coverage, what documentation a claim requires, whether legal defense costs are included, and whether subcontractors and customer lawsuits are covered. Vague answers here are a warning sign, not a formality.
Ask these commercial insurance questions before a claim happens, not during one. A policy that sounds comprehensive in a sales conversation can turn out to be narrow once you read the trigger conditions and documentation requirements in the actual contract language.
What Isn’t Covered by My Insurance?
Standard commercial insurance questions policies typically exclude flood and earthquake damage, intentional acts, prior acts (incidents before a claims-made policy’s retroactive date), professional-services claims under a general liability policy, and employee theft. Each of these needs a separate policy or endorsement if it’s a real risk for your business.
Missing an exclusion is one of the costliest insurance mistakes an owner can make usually discovered only when a claim gets denied. If you’re in a flood zone, handle client advice, or carry inventory employees can access, ask specifically whether those gaps apply to you before you need to find out the hard way.
How Much Coverage Do I Really Need?
Coverage adequacy comes down to your policy limits the per-occurrence limit (max paid per claim) and the aggregate limit (max paid per policy period) matched against your industry risk, business size, location, and any contractual requirements from clients or landlords. A common small-business starting point is $1 million per-occurrence / $2 million aggregate for general liability, though high-risk fields like construction or healthcare typically need more.
Don’t buy blind to your contracts. Client agreements often specify minimum coverage requirements, and commercial leases frequently require property coverage before a landlord will sign check both before you assume your existing limits are sufficient.
What Factors Affect Business Insurance Costs?
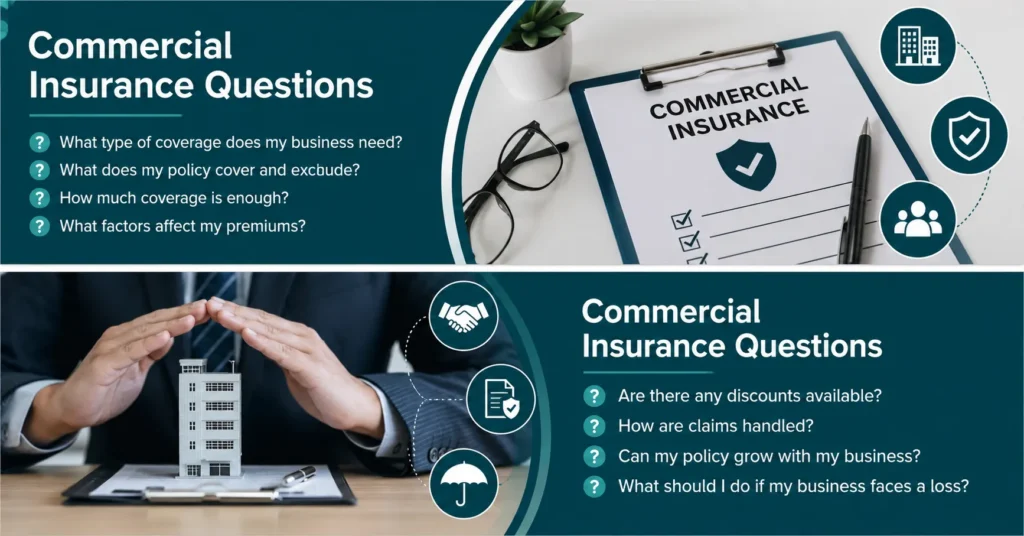
Insurers price commercial insurance questions policies based on industry, payroll, revenue, claims history, vehicles, and location plus newer underwriting factors like cybersecurity controls, climate exposure, and remote-workforce risk. A restaurant with constant foot traffic pays differently than a home-based consultancy, and that gap is by design, not inconsistency.
You do have levers to pull. Raising your deductible, bundling policies into a BOP, maintaining a clean claims history, and tightening physical or cyber risk controls can all bring your premium down without cutting real protection.
What Are the Legal Requirements for Business Insurance?
commercial insurance questions requirements vary by state and industry, but most states require workers’ compensation and commercial auto insurance once you have employees or company vehicles. General liability, while often not legally mandated, is close to a practical necessity for most operating businesses.
Don’t assume your state’s minimums are your ceiling. “Legally required” and “adequately protected” are two different bars plenty of businesses that meet every legal requirement are still dangerously underinsured for the actual risks they carry day to day.
Do I Need Insurance If I Use Independent Contractors or Freelancers?
Independent contractors are usually excluded from your business insurance policies since your rates are priced around your own employees and safety protocols, not self-employed workers. That doesn’t mean the risk disappears it means the responsibility shifts to verification.
Protect yourself by requiring contractors to carry their own general liability, professional liability, and (where applicable) workers’ comp coverage, and by collecting a certificate of insurance (COI) before work begins. Adding yourself as an “additional insured” on their policy extends real protection if something goes wrong on a shared project.
How Do I Choose the Right Insurance Provider?
Start with the basics: what’s included and excluded in the policy, how claims are filed and processed, and whether bundling lowers your premium. Beyond price, look for a provider that understands your specific industry and communicates clearly before you ever need to file anything.
How Easy Is It to File a Claim and Get Proof of Insurance?
Test this before you’re desperate for it. Ask how quickly the insurer typically resolves and pays claims, whether digital certificates of insurance are available on demand, and what the actual claims communication process looks like a policy is only as good as how it performs on your worst week.
Is There Insurance for Remote Employees?
Yes remote and hybrid work changes your exposure in ways a standard office-based policy won’t cover. Employee injuries at a home workstation, cyberattacks through unsecured home networks, and damage to company equipment kept off-site all fall outside typical homeowner’s or renter’s coverage.
Workers’ comp still applies to remote injuries in nearly every state, cyber insurance covers the added breach risk of distributed work, and business personal property (BPP) coverage protects equipment you’ve sent home with staff. If remote workers ever drive for business errands, you’ll also need hired and non-owned auto coverage, since personal auto policies won’t step in for work-related driving.
How Will My Insurance Needs Change as My Business Grows?
Your risk profile shifts every time your business does hiring employees or subcontractors, buying expensive equipment, signing larger contracts, adding locations, or growing revenue all change what “adequate coverage” means. A policy that fit you at launch can quietly become insufficient two years later without anyone noticing until a claim exposes the gap.
Can I Cancel or Adjust My Policy?
You can typically adjust coverage anytime by contacting your agent, and cancel outright, though early cancellation often carries a fee. The better habit is a scheduled annual review most owners find it easier to catch gaps proactively than to discover them during a claim.
Conclusion
Choosing the right commercial insurance questions starts with asking the right questions. Whether you are reviewing coverage, comparing policies, or preparing to protect a growing business, understanding your risks can help you avoid costly surprises later. The key is to look beyond price and consider coverage limits, exclusions, deductibles, liability protection, and the specific needs of your industry.
A good insurance professional should also be willing to explain unclear terms and help you identify potential gaps. Taking time to ask thoughtful questions now can make your policy easier to understand and more useful when you actually need it. The right coverage gives you greater confidence to focus on running and growing your business.
FAQs
Author
Hi, I’m Alex, and I enjoy learning through quizzes, trivia, and interactive questions. I love discovering new conversation starters, relationship topics, and educational challenges. This website is my go-to place for fun, practical, and reliable question-based content. I’m always excited to learn something new and share it with others.